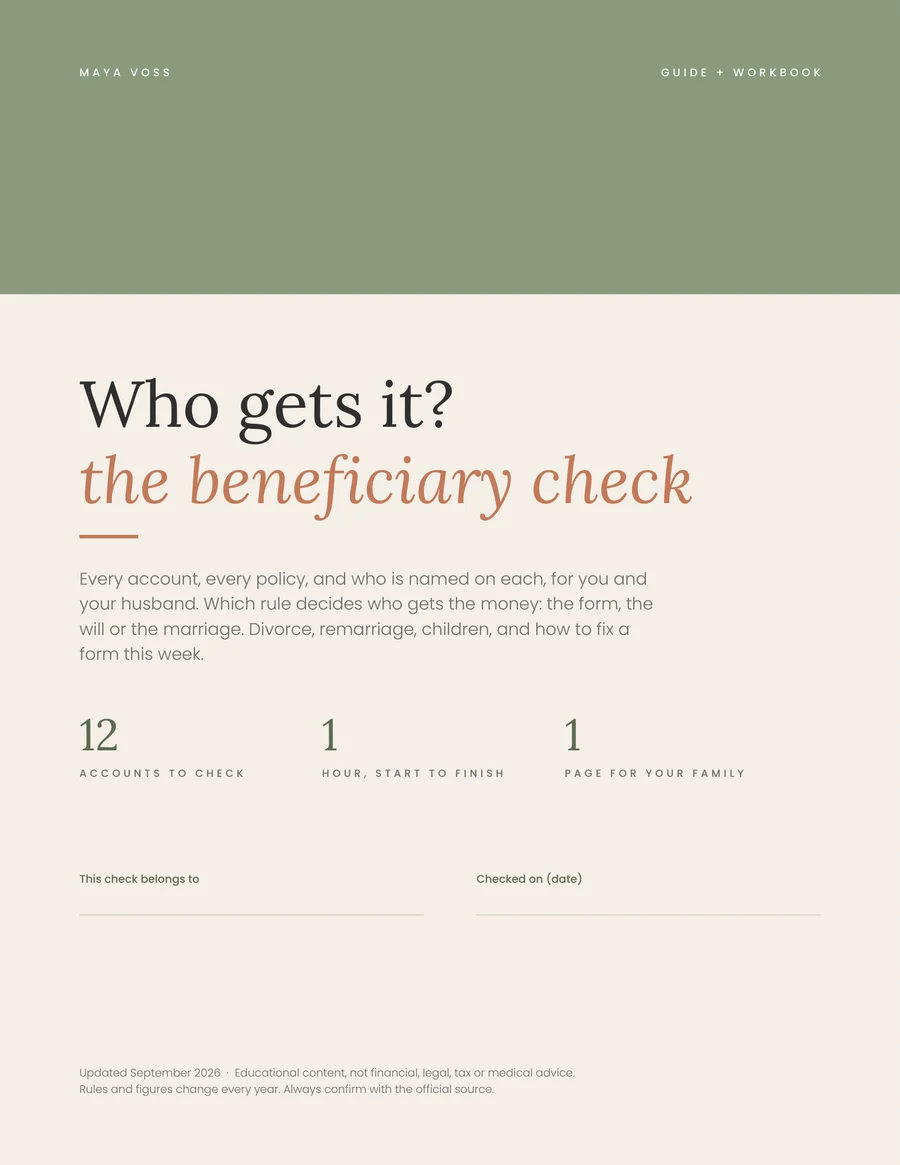
Who gets it? The beneficiary check.
Your 401(k), your IRA, your life insurance: each goes to the person named on its form, not in your will. Often a form filled out decades ago. For you and your husband: see who is named on every account, and fix it in one evening.
Written after a Threads post about a widow and a life insurance form was seen more than 130,000 times.
What one old form can cost
1 form
Decides who gets a 401(k), an IRA or a life insurance policy. Usually not the will, often not the divorce papers.
$400,000
Paid to an ex-wife who had given it up in the divorce, because the form still named her (Supreme Court, Kennedy v. DuPont, 2009).
2 words
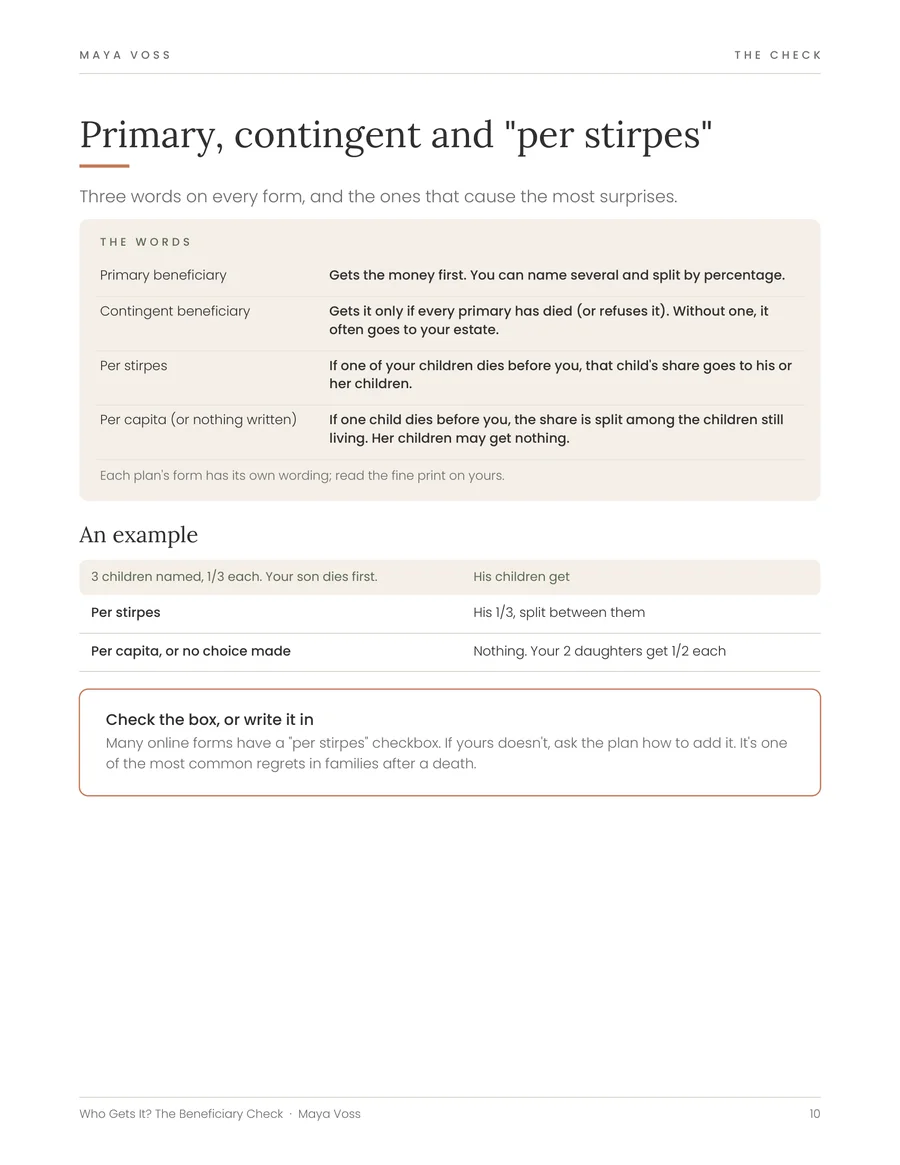
"Per stirpes." Missing on many forms, and without them grandchildren can be left out if their parent dies first.
Checking every form, yours and his, takes one evening with this guide: $22.
What it solves
"My will takes care of it."
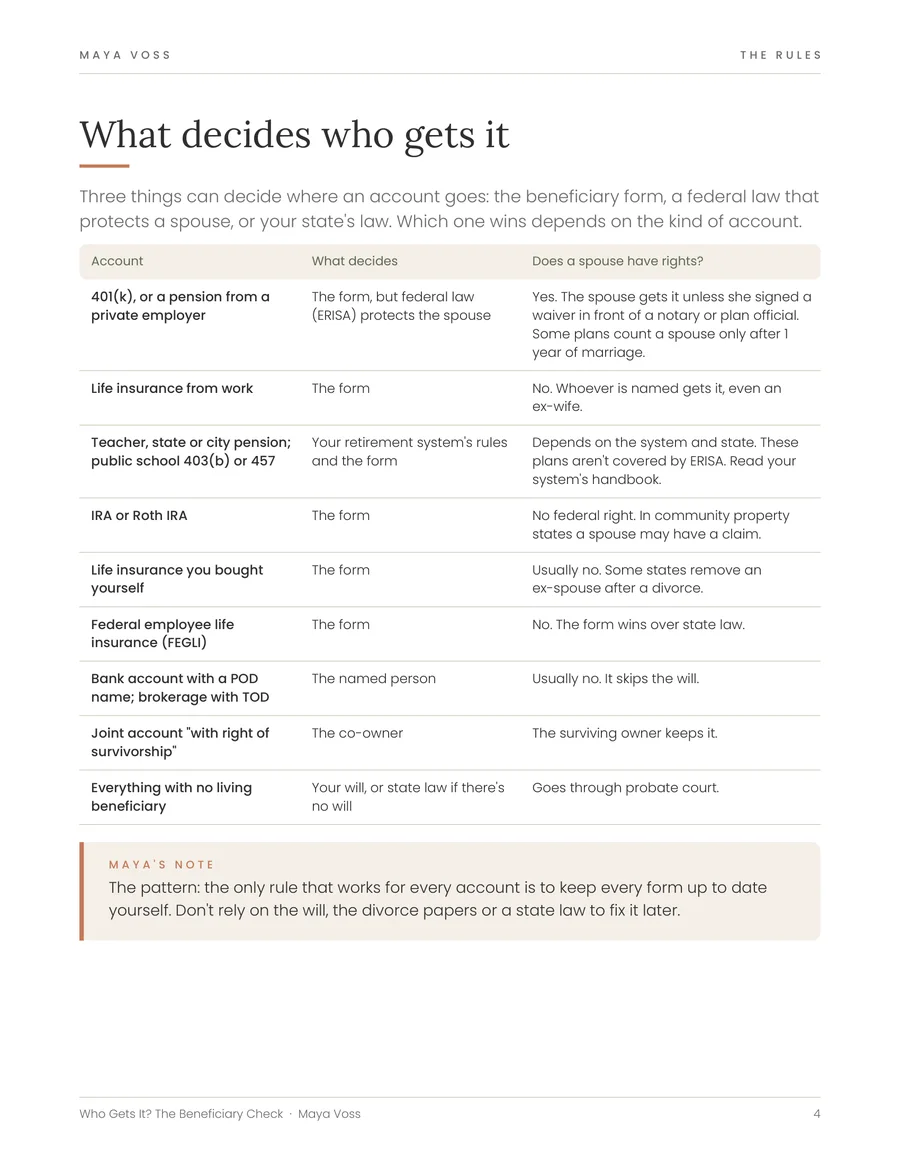
Not for most accounts. A one-page table shows what decides each one: the form, a federal law that protects a spouse, or your state's law.
"We're divorced. She's off his policy, surely."
Not unless someone changed the form. Four Supreme Court cases show how it plays out, and the divorce page shows what to do.
"I named my kids. That's enough."
Contingents, "per stirpes", and why a child under 18 shouldn't be named directly, so your grandchildren aren't left out by one missing word.
Instant download · 30-day money-back guarantee
What's inside
- The rules: what decides who gets each account, four Supreme Court cases, divorce, remarriage and widowhood
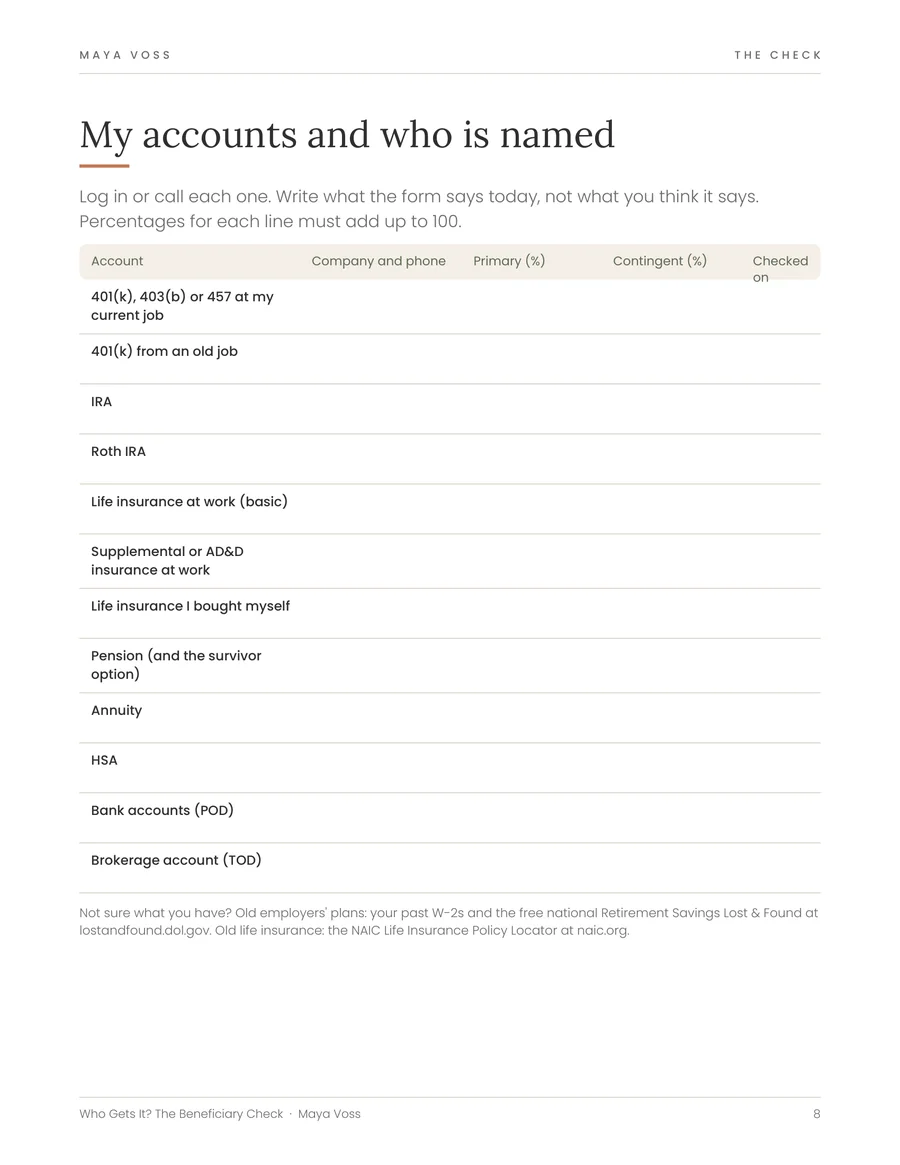
- The check: my accounts and who is named, my husband's accounts, primary, contingent and "per stirpes"
- Who not to name, and what to do instead (minors, "my estate", someone on SSI or Medicaid)
- What heirs owe in taxes: life insurance, inherited IRAs and the 10-year rule, HSAs
- Fixing it: how to change each form, the open enrollment check, the talk word for word
- Where everything is, one page for your family, and free help
Hi, I'm Maya. Here's why I wrote this.
What happens after you pay
- 1
Pay once, by card
A secure card page, about a minute. No subscription, nothing to cancel.
- 2
Your PDF opens right away
A download button appears as soon as you pay, and a copy arrives in your email.
- 3
Do the first step tonight
Check three forms tonight: life insurance at work, your 401(k), your IRA (page 8).
Instant download · 30-day money-back guarantee
Questions
Who is it for?
Anyone with a retirement account, a pension or life insurance, married, remarried, divorced or widowed, in any state. Most useful if you haven't looked at your forms in years, or if your family has changed since.
Will the price go up?
Yes. The discount at the top of this page has a real timer: when it runs out, you pay the regular, crossed-out price. The timer does not restart.
Is this legal advice?
No. It shows you what's on your forms and which rules usually apply, so you can fix the simple things yourself and know when to ask an attorney. Laws differ by state, and the guide says where.
How do I know it's right?
Every rule comes from a public source: Supreme Court decisions, the U.S. Department of Labor, the IRS and Social Security. They're listed on the last page so you can check each one.
I'm a teacher with a state pension. Does it apply?
Yes, with one difference it explains: public pensions and public school 403(b) and 457 plans follow your retirement system's rules, not the federal law for private plans. The guide shows what to ask your system.
What if it doesn't help me?
Email support@tamify.store within 30 days and you get a full refund. No questions, no forms.
How does payment work?
You pay by card on a secure page run by our payment provider, in US dollars. The provider is based outside the US, so some cards may add a foreign transaction fee: your card issuer can tell you. Right after payment a download button appears, and a link arrives by email.
Instant download · 30-day money-back guarantee