Medicare, without the penalties.
Miss your Medicare window, or count on COBRA, and your Part B bill can go up every month, for life. For you or your husband: find your dates in 5 minutes, check if your coverage counts, and avoid every penalty.
Written after a Threads post about the Medicare window was seen more than 90,000 times.
What one missed date can cost
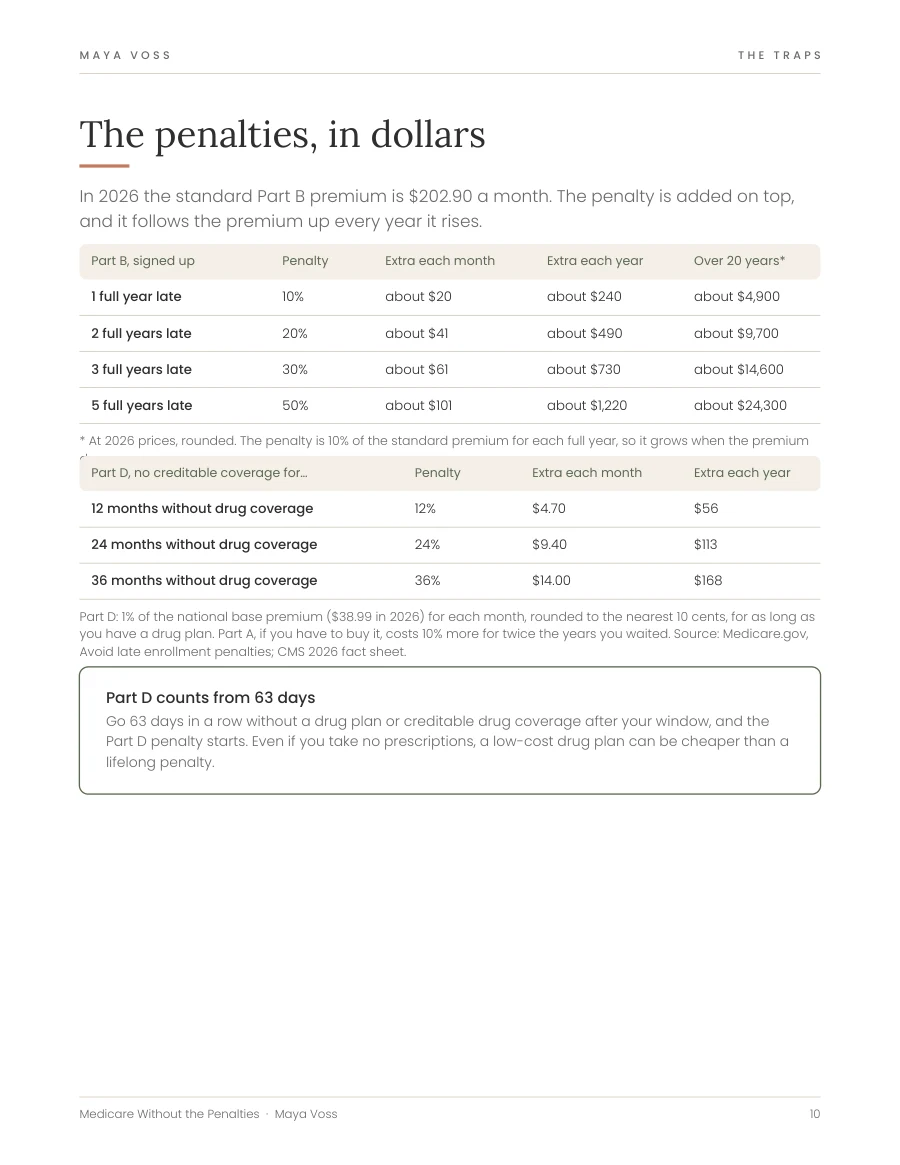
$243 a year
Extra on Part B for signing up 1 full year late, at 2026 prices. For as long as you have Part B.
$487 a year
For signing up 2 full years late. Medicare's own booklet shows this exact math.
6% a year
Tax on HSA money put in after Medicare starts, every year until it's taken out.
The guide that helps you avoid all three: $22.
What it solves
"When exactly do I sign up?"
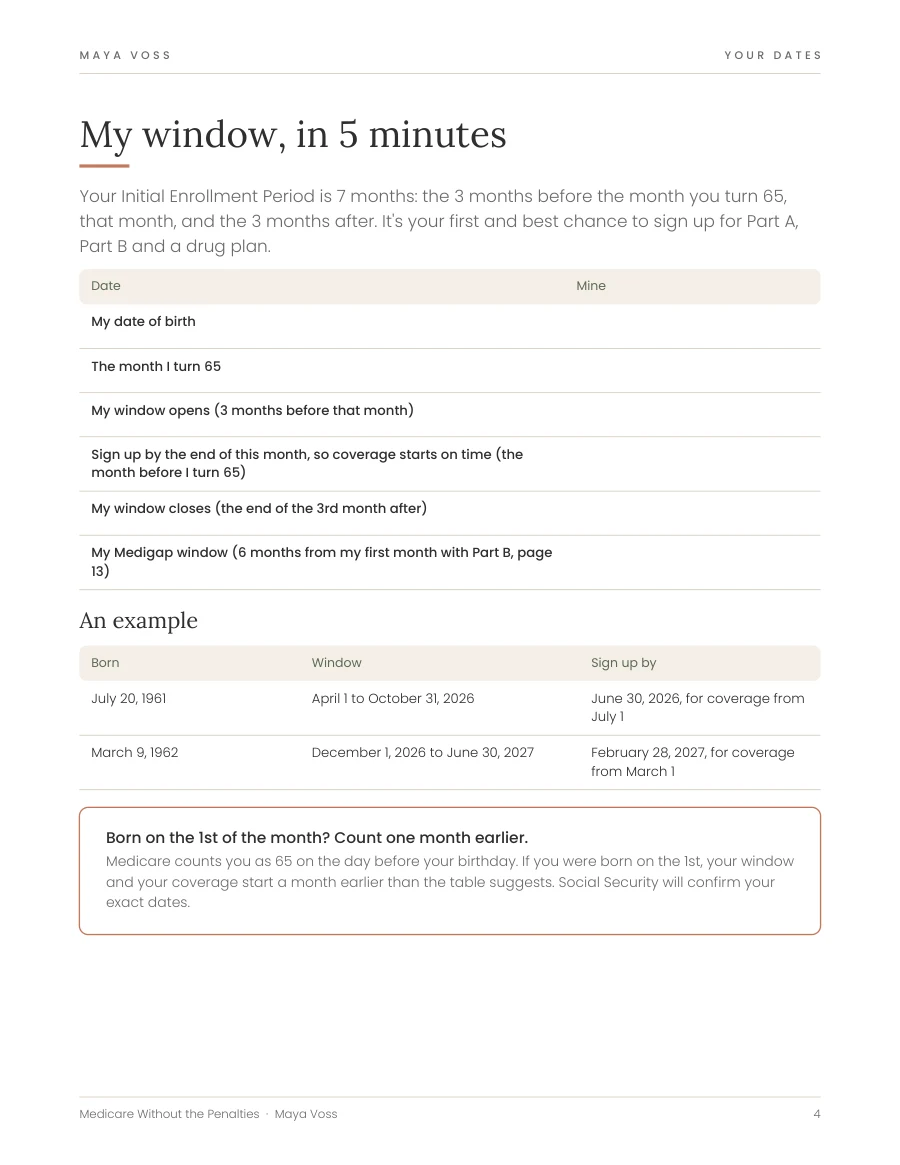
Your own 7-month window on paper in 5 minutes, the month to sign up so coverage starts on time, and what happens if you were born on the 1st.
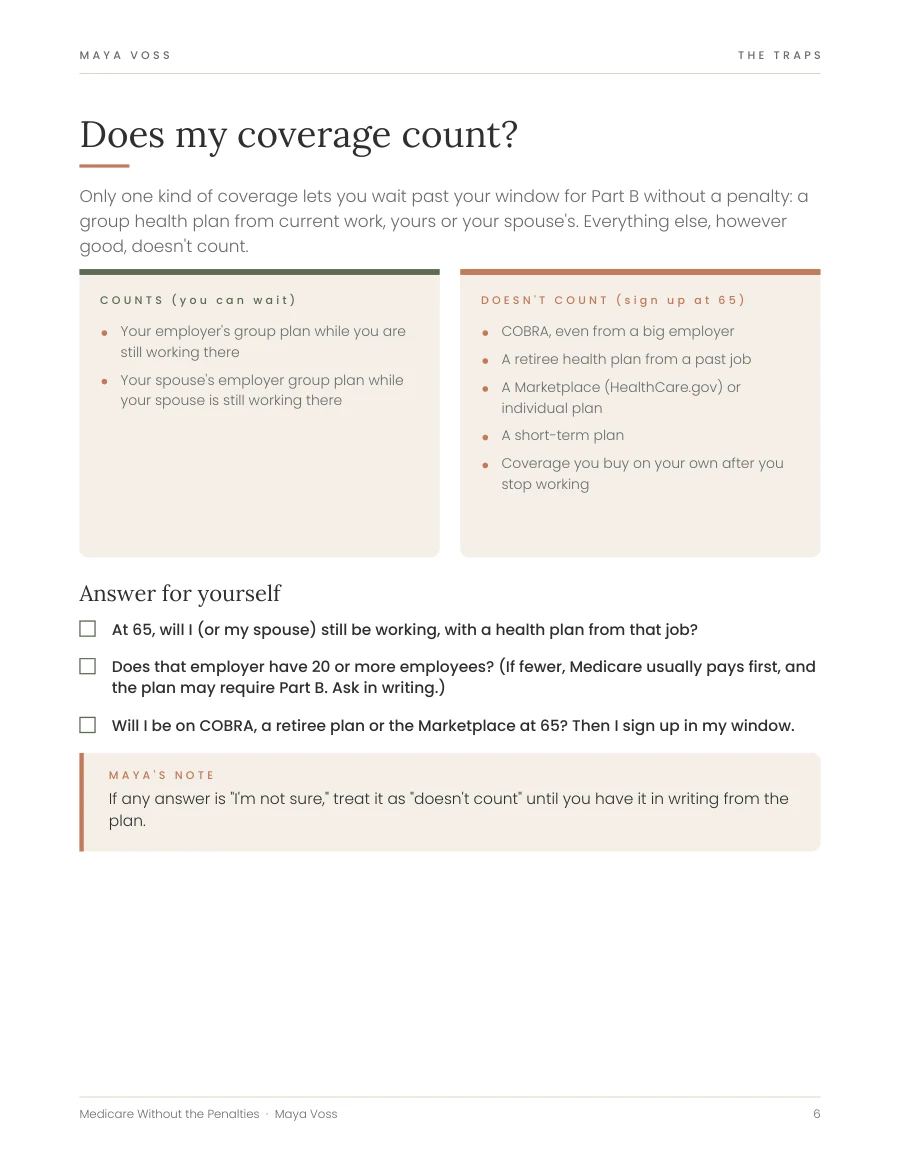
"I have COBRA or my old job's plan. I'm covered, right?"
Covered for doctors, maybe. Protected from the penalty, no. One page shows exactly which coverage counts and which doesn't.
"I'm still working, or he is."
When you can safely wait, the 8-month window after work ends, the two forms, and the HSA rule that catches people out.
Instant download · 30-day money-back guarantee
What's inside
- Your dates: my window in 5 minutes, and when coverage starts
- The traps: does my coverage count, COBRA and retiree plans, still working, the HSA trap
- The penalties in dollars: Part B and Part D, at 2026 prices
- Medicare, clearly: the parts, 2026 costs, the quiet Medigap window, Medigap or Advantage, drugs and doctors, IRMAA, when one of you gets Medicare first
- Doing it: how to sign up step by step, already late, my countdown, questions to ask word for word
- My Medicare plan on one page, and free help in your state
- Every 2026 figure from medicare.gov, cms.gov and ssa.gov
Hi, I'm Maya. Here's why I wrote this.
What happens after you pay
- 1
Pay once, by card
A secure card page, about a minute. No subscription, nothing to cancel.
- 2
Your PDF opens right away
A download button appears as soon as you pay, and a copy arrives in your email.
- 3
Do the first step tonight
Fill in "My window, in 5 minutes" on page 4. Every other date hangs on it.
Instant download · 30-day money-back guarantee
Questions
Who is it for?
Anyone getting closer to Medicare, or married to someone who is: still working, retiring early on COBRA or a retiree plan, or already on Medicare and not sure it was done right. Any state. It's most useful a few years ahead, so nothing is a surprise.
Will the price go up?
Yes. The discount at the top of this page has a real timer: when it runs out, you pay the regular, crossed-out price. The timer does not restart.
Will it tell me which plan to choose?
No. It isn't an insurance agent and sells no plans. It helps you avoid a penalty by accident, and go into the plan choice with your dates, your drugs and your questions ready. For free one-on-one help it points you to your state's SHIP.
I'm already past my window. Is it too late?
It may not be too late to limit the damage. One page is about exactly that: Special Enrollment Periods, including the newer "exceptional conditions" ones, the General Enrollment Period, and what to do this month.
How do I know it's right?
Every rule in it comes from medicare.gov, cms.gov, ssa.gov, irs.gov or dol.gov, and the sources are listed on the last page, so you can check each one. Rules and figures change every year: confirm your own case with Social Security or your state's free SHIP counselor.
What if it doesn't help me?
Email support@tamify.store within 30 days and you get a full refund. No questions, no forms.
How does payment work?
You pay by card on a secure page run by our payment provider, in US dollars. The provider is based outside the US, so some cards may add a foreign transaction fee: your card issuer can tell you. Right after payment a download button appears, and a link arrives by email.
Instant download · 30-day money-back guarantee